Best Cash ISA, Savings & Fixed Deposit Rates UK – September 2026
Transparency Disclosure: To keep our guides free for everyone, this post contains affiliate links and display advertisements. If you click an affiliate link and sign up, we may earn a commission at no extra cost to you. As an ex-banker with 25 years of experience, I only recommend tools that I believe provide genuine value to your financial health. Read our full Affiliate Disclosure here.
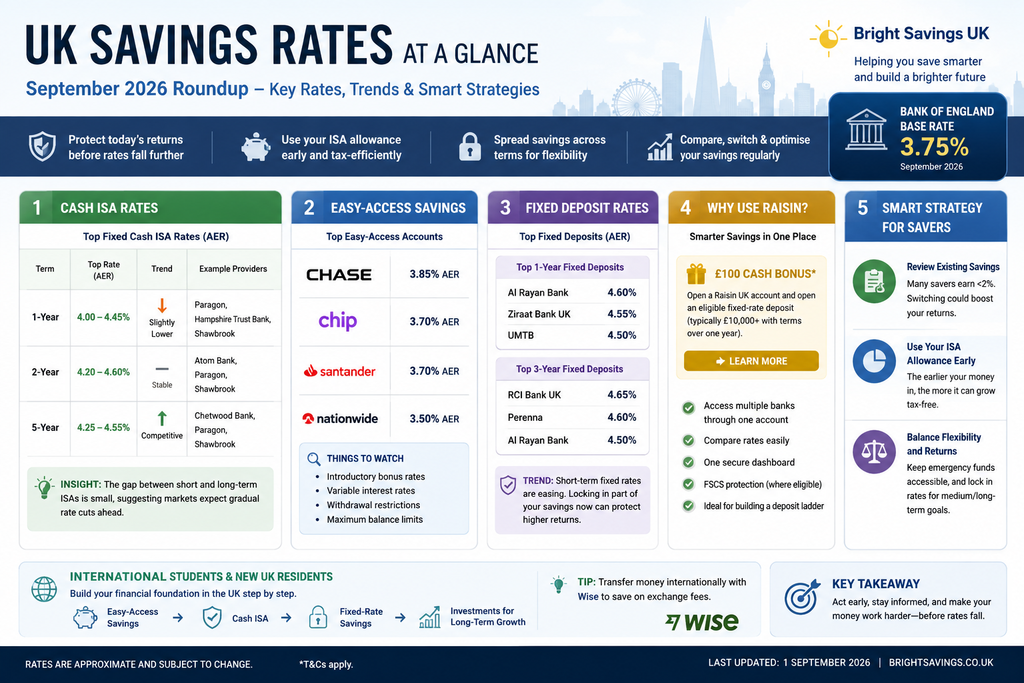
📊 Monthly UK Interest Rate Roundup – Bright Savings UK
September begins with savings rates remaining highly competitive, but the market is more complex than the simple downward trend expected earlier in 2026.
The Bank of England has kept Bank Rate at 3.75%, while inflation has moved up to 2.9%. This has encouraged providers to keep selected savings rates elevated and has made the timing of fixed-rate decisions more important.
This month’s update covers:
✅ Latest Cash ISA rates
✅ Best easy-access savings accounts
✅ Updated fixed deposit rates
✅ Smart strategies for the autumn and final months of 2026
✅ Smart strategies for the second half of 2026
📊 1. UK Interest Rate Snapshot – September 2026
- Bank of England Base Rate: 3.75%
- Inflation: 2.9% (latest available July 2026 CPI)
- Savings rates remain attractive, with leading deals around 5% AER in some categories
📅 Data checked: 1 September 2026. Rate examples use the latest available market data published in late August; savings products can change or be withdrawn without notice.
- Providers continue repricing products as inflation and future Bank Rate expectations change
💡 Key Takeaway
The market has shifted from a straightforward rate-cut story to a more uncertain environment. With Bank Rate at 3.75% and the next MPC decision due on 17 September, savers should compare both variable and fixed options rather than assume rates will simply fall.
For savers with larger cash balances, the gap between a market-leading account and a low-paying account can still be significant. Tax efficiency is also becoming more important as savings interest increases.
💷 2. Best Cash ISA Rates – September 2026 (latest market data)
Cash ISAs remain one of the most tax-efficient ways to hold cash because qualifying interest is free from UK income tax.
🥇 Top Fixed Cash ISA Rates
| Term | Top Rate (AER) | Trend | Example Providers |
| 1-Year | ~4.72–4.90% | Competitive | AlRayan Bank, Marsden BS, Vida Savings |
| 2-Year | ~4.77–4.95% | Competitive | Vida Savings, Investec Save, Shawbrook |
| 5-Year | ~4.85–4.87%+ | Competitive | Marsden BS, Vida Savings, Hinckley & Rugby BS |
💡 Insight
The latest available market data shows that fixed Cash ISA rates have become more competitive. At the end of August, leading rates were approaching 4.9%, with longer-term fixes currently offering some of the highest headline rates.
This means the decision is no longer simply about taking the shortest term. Savers should compare the rate, term, access rules and whether they are comfortable locking away the money.
🏦 3. Best Easy-Access Savings Accounts – September 2026
Some of the strongest easy-access savings accounts in the latest August market data include:
- LemFi Instant Access Savings Account – 5.00% AER including a temporary bonus
- Tembo Money HomeSaver – 4.55% AER including bonus
- First Active Instant Access Savings Account – 4.55% AER including bonus
- Tesco Bank Internet Saver – 4.53% AER including bonus
⚠ Things to Watch
- Introductory bonus rates
- Variable interest rates
- Withdrawal restrictions
- Maximum balance limits
💡 Trend
Bonus rates can make a headline rate look more attractive than the long-term rate. Check when the bonus ends and what the account will pay afterwards.
Reviewing your savings account every few months can make a meaningful difference, particularly when variable rates and introductory bonuses are changing quickly.
🔐 4. Fixed Deposit Rates – September 2026 (latest market data)
Fixed-rate savings remain attractive for savers who want certainty and do not need access to their money during the fixed term.
🥇 Top Fixed Deposits
- Shawbrook– around 4.84% AER for 1 year
- Shawbrook – around 4.81% AER for 2 years
- ICICI Bank UK Plc / Afin Bank – around 4.80% AER for 5 years
Latest market data indicates that leading fixed-rate bonds are around 4.8–4.9% AER, depending on term and provider.
🥇 What This Means
- Longer-term rates are currently competitive, with some 5-year products reaching around 4.80% AER.
- However, fixing for longer means giving up flexibility. Consider whether you may need the money before the maturity date.
Compare the total return, access rules, minimum deposit and FSCS protection before opening an account.
💡 Trend Insight
Locking in part of your savings can provide certainty if rates later fall, but a diversified maturity strategy can reduce the risk of fixing everything at the wrong time.
Locking in part of your savings today could help preserve higher returns if rates continue to fall later this year.
⭐ 5. Why Raisin Remains Worth Considering
As banks and savings providers adjust their products more frequently, comparison platforms can be useful for checking a range of fixed-rate accounts in one place.
Receive a £100 Cash Bonus*
Open a Raisin UK account and open an eligible fixed-rate deposit. Check the current qualifying deposit, term and promotional conditions before applying.
👉[Link]
Benefits
✅ Access multiple banks through one account
✅ Compare rates easily
✅ One secure dashboard
✅ FSCS protection (where eligible)
✅ Ideal for building a deposit ladder
💡 Expert Insight
Instead of putting all your savings into one fixed term, many experienced savers spread deposits across different maturity dates. This ‘deposit ladder’ can provide a balance between competitive returns and future access.
📈 6. What This Means for Savers
1️⃣ Review Existing Savings
Some savers remain in accounts paying far below the market-leading rates.
Switching or reviewing providers could substantially improve returns, although always check withdrawal rules, bonuses and provider protection.
2️⃣ Use Your ISA Allowance Strategically
Using ISA capacity can become increasingly valuable when taxable savings rates are high. Remember that the overall ISA allowance remains £20,000 for 2026/27.
3️⃣ Balance Flexibility and Returns
A sensible approach may include:
- Emergency savings in easy-access accounts
- Fixed deposits for medium-term goals
- Cash ISAs for tax efficiency
🌍 7. Special Note for International Students & New UK Residents
If you’re building your finances in the UK:
Start with:
➡ Easy-access savings
Then gradually consider:
➡ Cash ISA
➡ Fixed-rate savings
➡ Investments for long-term wealth building
💡 Tip
If you’re transferring money from overseas, using Wise can often reduce exchange costs compared with traditional banks, but always compare the total exchange rate and fees.
🔮 8. Outlook for the Rest of 2026
The latest market backdrop suggests:
- · Bank Rate may remain at 3.75% in the near term, with the next decision on 17 September 2026
- · Savings rates may remain competitive while inflation is elevated
- · Fixed-rate products could remain attractive, but pricing may change quickly
- · ISA providers are likely to continue competing for transfers and new deposits
💡 Key Message
While the outlook is less predictable than it appeared earlier in the year, savers still have an opportunity to secure competitive returns. The key is to avoid relying on a single forecast about interest rates.
For many savers, a balanced strategy—combining easy access, fixed terms and tax-efficient savings—may be more robust than trying to time the market perfectly.
🧠 9. September 2026 Saver Checklist
✔ Review all savings accounts
✔ Check if bonus rates are ending
✔ Review how much of your ISA allowance you have used
✔ Compare rates monthly
✔ Consider fixing part of your savings if you won’t need the money soon
✔ Keep emergency funds accessible
✔ Review your strategy before the September and November Bank of England meetings
Why Trust Bright Savings UK?
Bright Savings UK is run by a former banker with over 25 years of experience in the banking and financial services industry. Our goal is to help everyday people save smarter, with clear explanations and practical guidance.
Suggested Internal Links
- Average Savings in the UK by Age [Link]
- Average ISA Savings in the UK by Age [Link]
- Average Pension in the UK by Age [Link]
How We Monetize This Site
To support the research and running of Bright Savings UK, we use two primary methods of monetization:
- Affiliate Links: Some links on this site are affiliate links. If you click and open an account, we may receive a commission. This does not change the price or terms you receive from the provider.
- Display Advertising: We host third-party advertisements through Google AdSense. We do not directly control the specific products shown in these ad units, and their presence does not constitute an endorsement by Bright Savings UK.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Investing involves risk. Capital is at risk, and you may lose money. Always review provider terms directly before applying.